Weekly Brief / Issue 10
China Capital Markets Weekly: Airline Growth Meets the Balance Sheet
Loong Airlines' reply brings fleet financing into view, while review decisions and Beijing measures put the week's milestones in context
9 min read
An airline can grow its fleet without owning every aircraft, but the lease payments still have to be funded. Loong Airlines' first-round response examines that distinction alongside maintenance costs, payables and liquidity. Langgao advances to registration submission, three applications end, and Beijing's regulatory measures address fund disclosure and the outsourcing of advisory communications.
Contents
A larger fleet comes with a payment schedule
Loong Airlines' first-round IPO response, published on September 23, places the airline's growth alongside the obligations that make it possible. Aircraft can be bought, leased or financed through arrangements that leave different marks on the balance sheet. None of those routes makes the cost of expansion disappear.
The response covers fifteen groups of questions. Aircraft and leases, long-term deferred expenses, solvency, payables and derivatives sit beside the familiar questions about revenue, procurement and margins. For readers trying to understand the business, those balance-sheet sections are as important as passenger demand.
The week also brought a ChiNext committee pass for Suzhou Langgao Electric Motor and the end of three other applications. In Beijing, regulatory measures concerned the information fund managers owe investors and the responsibility advisers retain for their online communications.
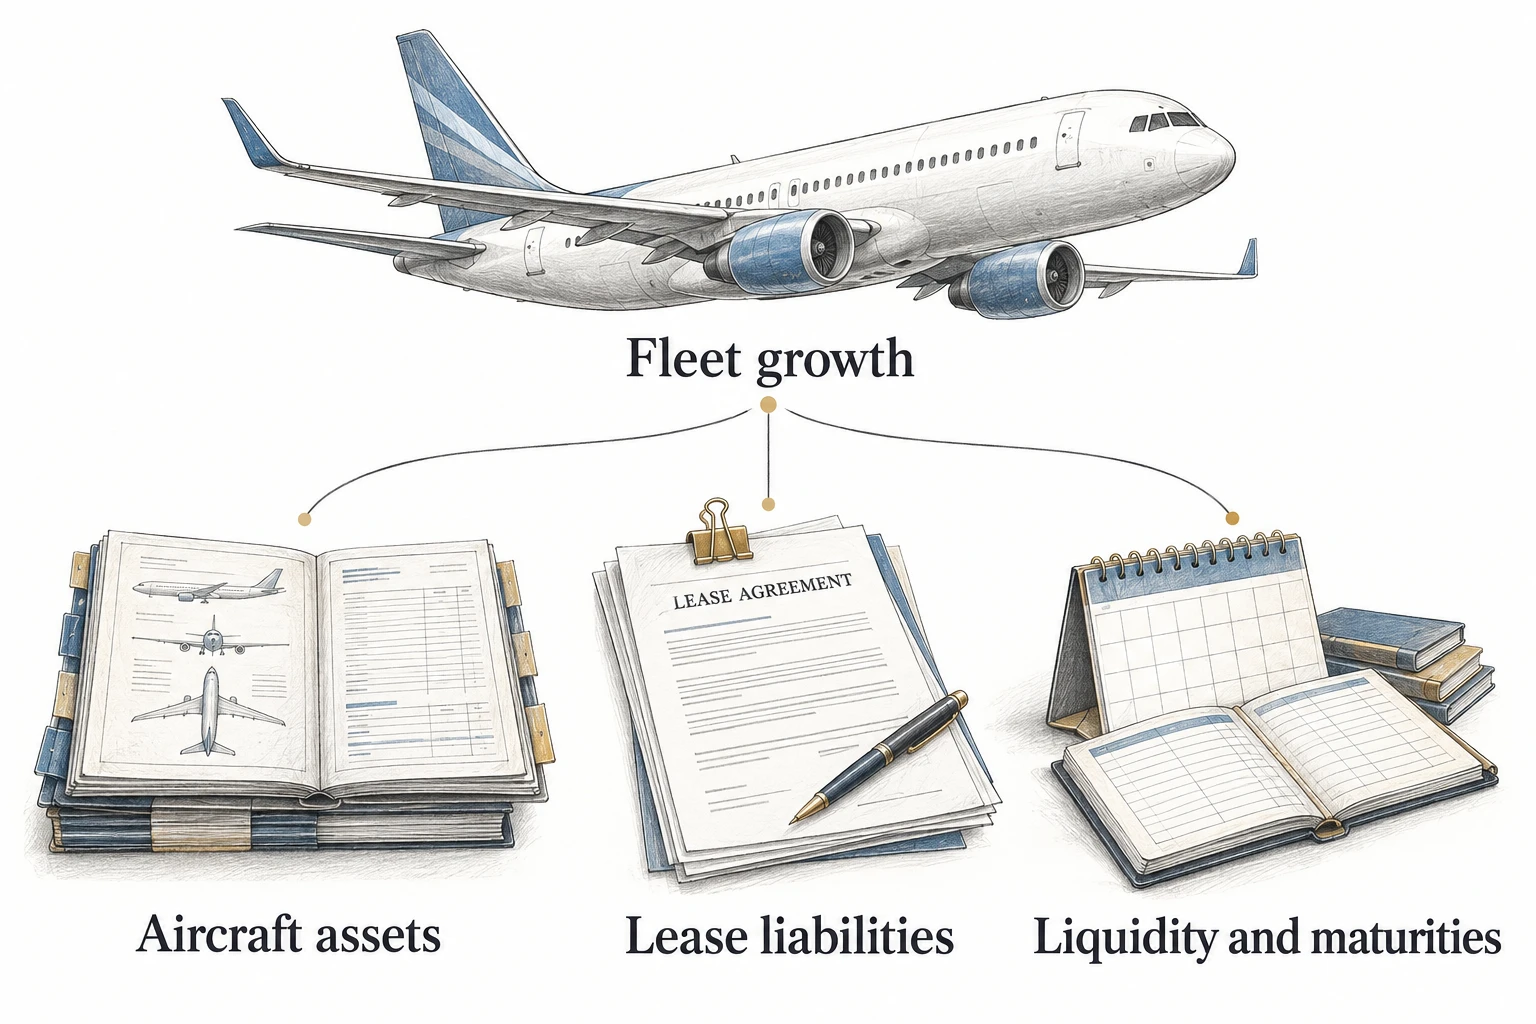
The aircraft is only the beginning of the cost
An owned aircraft generally appears within fixed assets. A leased aircraft can appear as a right-of-use asset with a corresponding lease liability. Both arrangements support operations, but they have different cash requirements, financing terms and residual-value exposure.
A useful comparison therefore goes beyond counting aircraft. It considers purchase commitments, lease maturities, deposits, maintenance obligations, interest and foreign-currency exposure. An airline may report growing revenue while a larger share of future receipts is already needed for payments on its fleet.
Loong's response includes aircraft and lease questions alongside long-term deferred expenses. Maintenance can involve substantial expenditure whose accounting recognition and cash payment fall in different periods. The relevant explanation should identify the work performed, the period over which the benefit is expected and the basis for allocating the cost. Capitalizing expenditure spreads an expense; it does not reverse the payment.
Payables introduce another timing difference. Supplier credit can support cash flow during expansion, but it is still funding that will have to be settled. Other receivables deserve their own explanation: their counterparties, purpose, recoverability and expected settlement determine whether they are usable resources or simply claims recorded on the balance sheet.
Currency risk can run through several parts of the business. Aircraft financing or other obligations may be denominated in a currency different from the airline's receipts. Derivative contracts can change that exposure, but their terms, maturity and cash requirements matter more than the mere presence of a hedge.
These are the financial questions raised by the Loong Airlines response. They do not establish that the airline is unable to meet its obligations. They explain why fleet expansion should be read together with the resources and payment schedules supporting it.
A credit line is not cash already in the bank
Loong's reply makes the distinction concrete. At the end of 2025, 63 of its 76 aircraft were recognized through right-of-use assets and lease liabilities, or 82.89%. That count excludes sale-and-leaseback aircraft. The company explains its greater reliance on leasing by its narrower financing channels: buying aircraft outright would use more cash immediately.
In its forward twelve-month liquidity estimate, based on balances at the end of 2025, Loong sets out the following amounts:
| CNY billion, rounded | Company's estimate |
|---|---|
| Surplus from ordinary operating receipts and payments | 2.419 |
| Investment payments | (1.320) |
| Debt principal, fleet rent and bank interest payments | (11.234) |
| Net funding requirement, as reported | (10.119) |
| Available cash at the reporting-period end | 1.982 |
| Unused bank credit facilities | 14.655 |
| Cash plus unused facilities | 16.637 |
Source: first-round response, PDF pp.251–254. This is the company's forward-looking funding estimate, not a cash-flow statement for the next twelve months. The operating surplus excludes aircraft and engine lease payments, which appear separately in the payment schedule.
Adding the three cash-flow lines gives a funding requirement of approximately CNY10.135 billion, rather than the CNY10.119 billion reported in the reply. The CNY15.8 million difference needs a reconciliation; the table does not explain it.
Loong concludes that the combined resources exceed the estimated requirement and that it faces no major short-term repayment risk. It points to relationships with large banks, guarantees from its controlling shareholder and actual controller, and access to equity financing. Its debt-to-assets ratio also fell from 94.20% in 2023 to 89.92% in 2025, although the latter remained above the 82.54% listed-airline average used in the reply.
The financing case therefore depends on more than the CNY1.982 billion of available cash. Unused facilities account for most of the stated resources; drawing them would provide funds and create debt, rather than release cash the company already owns. Their availability, terms and timing matter alongside the assumptions about operating receipts. The company's own added risk disclosure acknowledges that unrestricted cash alone does not cover the forecast payments and that it continues to need debt financing.
This is not a claim that the banks will withdraw support. It identifies the support on which the calculation relies. Readers following the airline's expansion can test that explanation against subsequent borrowing, facility use and lease-payment disclosures.
What moved through the IPO process
| Applicant | Development during September 21–27 | Significance |
|---|---|---|
| Suzhou Langgao Electric Motor | Passed the ChiNext listing committee on September 22; submitted for registration on September 23 | The application moved from exchange review toward the registration stage. |
| Huandong Robot Joint Technology | Shanghai exchange termination decision on September 21 | The application ended; termination should not automatically be described as a committee rejection. |
| Shanghai Huihe Medical Technology | Shanghai exchange termination decision on September 24 | The review ended under a formal exchange decision. |
| Guangxi Tianyuan Biochemical | Shenzhen exchange termination decision on September 24 | The applicant withdrew its application, and the exchange ended review. |
A committee pass is not the same event as registration approval, and registration approval is not the same event as the start of trading. These distinctions matter when following a company from application to listing. The Shanghai and Shenzhen project records provide the procedural trail.
Nanjing Autotuo's project record was updated on September 22 after a registration decision dated September 18. The later update tells readers where the project stands; it does not move the underlying decision into this reporting week. Similarly, a termination records the end of a particular application, not necessarily an adverse judgment on every aspect of the business.
Other replies ask when growth becomes revenue and cash
Dandong Dongfang Measurement and Control Technology's first-round reply joins questions about performance decline and seasonality with customers, procurement, current-account balances, inventories and capacity investment. A seasonal business needs a timeline that connects orders, delivery, acceptance, invoicing and collection. Otherwise, a strong period can obscure the expenditure and credit extended to produce it.
Guangdong Baolun Electronics' second-round response brings customer sign-off into the revenue discussion. Sign-off can be relevant evidence that a project has reached the contractual recognition point. Readers still need to know what installation or commissioning remains, whether the signatory has the authority to accept the work and how the recognized amount connects to subsequent collections.
Juli Automation's response links a major restructuring and advances to related parties with receivables, contract assets and cash flow. The transaction documents explain who acquired what and on which terms. The financial records then need to show how the resulting business converts accepted work into cash. A restructuring approval does not answer that second question.
Shenzhen Yunbao Intelligent's second-round reply, published on September 22, addresses DPU products, major cloud customers, losses and forward-looking information. A data processing unit handles work such as networking and data movement alongside the main computing processors. For a developer seeking commercial scale, validation by a customer, a small deployment and recurring volume orders are different milestones.
Customer concentration makes the profitability forecast especially sensitive to purchase volumes and timing. Research spending, product iteration, selling prices and margins need to fit those assumptions. A forecast that relies on a large customer's rapid adoption should also make the consequences of a slower rollout intelligible.
The replies describe different businesses, but they all bring the point of commercial completion into view: when the product has been accepted, when revenue can be recognized and when the company can expect payment.
Beijing measures concern duties that cannot be delegated away
On September 24, the Beijing bureau published a corrective order for Beijing Kangsi Capital Management. The manager had failed to provide investors with disclosure required by its fund contract. The decision required a rectification report within thirty days. Its former compliance and risk-control officer also received a warning letter.
The issue is not whether a manager published some information somewhere. The fund contract identifies the obligations owed to its investors. Those obligations need a reliable delivery process, records of what was sent and a clear allocation of responsibility when a required communication is missed.
A separate decision concerning Lu Xinghong and Zhang Chi addressed unqualified third parties' use of authenticated online accounts to publish advisory content and conduct marketing livestreams. The practitioners received warning letters.
An authenticated account can convey professional authority to readers even when somebody else is preparing or distributing the material. The regulatory consequence follows the responsibility attached to that channel. Outsourcing production does not, by itself, transfer the licensed practitioner's duties.
These decisions were dated September 17 or 18 and published during the reporting week. They are administrative regulatory measures, not fines imposed under an administrative penalty decision.
The next policy dates are already on the calendar
The consultation on the CSRC's private-fund fundraising proposal closes on October 4. Investor qualification, funding sources, account arrangements and the records supporting them remain the practical issues to follow as the proposal develops.
The futures-company measures take effect on January 1, 2027. Their transition periods differ by business and activity. A firm preparing for commencement needs to map its actual operations to the relevant provision rather than assume the longest deadline applies throughout.
For Loong, the next useful information will be the financial reconciliation behind the expansion: fleet commitments, lease payments, maintenance expenditure and the cash available to meet them. For the technology and equipment applicants, the same discipline takes a different form: forecasts need to survive the move from customer interest to accepted orders and cash receipts.
Sources
- Loong Airlines first-round response, September 23
- Yunbao Intelligent second-round response, September 22
- Shanghai IPO project records and original disclosure files
- Shenzhen IPO project records and original disclosure files
- Beijing bureau decision on Kangsi Capital Management
- Beijing bureau decision concerning Lu Xinghong and Zhang Chi
- CSRC private-fund fundraising consultation
- CSRC futures-company measures
Disclaimer
This article examines public records relating to the reporting period. It is for research and educational purposes and is not investment, legal or accounting advice, or a recommendation concerning any security. Official findings are attributed to the relevant authority; analytical observations are not findings of misconduct. Public documents may subsequently be corrected or supplemented.
Continue reading
View all records
Weekly Brief · 28 September to 4 October 2026
China Capital Markets Weekly: A Medical Approval Is Not Yet a Revenue Stream
Neuracle's brain-computer interface filing separates clinical progress from commercial revenue as semiconductor replies test the assumptions behind growth
Disclosure EvidenceCash Flow QualityRegulatory Scope & Timing
Weekly Brief · 14 to 20 September 2026
China Capital Markets Weekly: Chip Expansion and the Quality of Earnings
Chip-equipment and semiconductor replies connect technical claims with losses, assets and the economics of expansion
Accounting JudgmentsRevenue & CollectionRegulatory Scope & Timing